
← Back to Blog
Buying
First-Time Home Buyer Guide for Fairport, New York: Steps, Costs, and What to Expect
By Audrey Coon, Licensed Real Estate Salesperson
Empire Realty Group · DRE# 10401351230
September 18, 2026 · 10 min read
Buying your first home in Fairport, New York is one of the most meaningful financial decisions you will make, and the process has more moving parts than most people expect. This first-time home buyer guide for Fairport, New York walks you through every major step, from figuring out what you can afford to handing keys at closing, with local prices, timelines, and details specific to this Monroe County village.
1. What Makes Fairport Different for First-Time Buyers
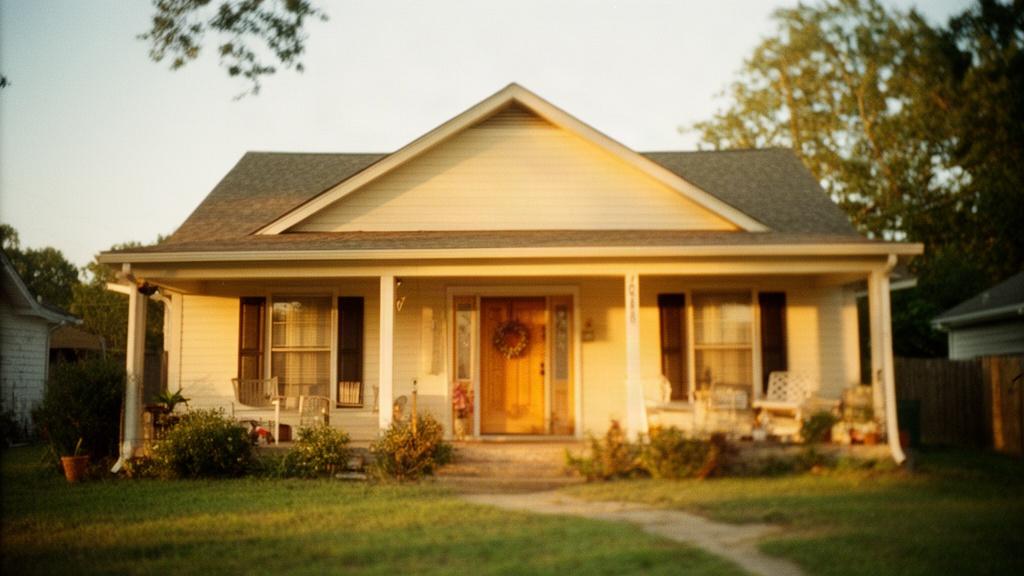
Fairport is a distinct market, not a generic suburb. The village sits about 10 miles east of downtown Rochester along the Erie Canal, and that geography shapes everything from the housing stock to the pace of sales. Homes here range from century-old Victorians and craftsman bungalows near the canal to split-levels and colonials built in the 1970s and 1980s further out in the surrounding town of Perinton, to newer construction in planned subdivisions on the eastern edges. Understanding that range before you start searching saves time and prevents surprises.
The Local Market in September 2026
Inventory in Fairport has remained tight through 2026. Homes priced correctly and in good condition are still moving quickly, often with multiple offers in the first week. First-time buyers who have not been pre-approved or who are unfamiliar with how fast this market moves tend to lose out to buyers who came prepared. For a current picture of how long homes are sitting and whether conditions favor buyers or sellers right now, see how long homes are staying on the market in Fairport NY.
Housing Stock and Price Ranges
Entry-level homes in Fairport and Perinton typically start in the low-to-mid $200,000s for smaller ranch or cape-cod styles that need updating. Move-in-ready colonials and larger split-levels commonly list in the $300,000 to $450,000 range. Homes directly in the Erie Canal village area, with walkable access to the lift bridge, Main Street restaurants, and the canal path, tend to command a premium and can push well above $400,000 depending on size and condition. For a detailed breakdown of what prices look like right now, the article on home prices in Fairport NY in September 2026 goes deeper on current figures.
2. Getting Your Finances Ready Before You Search
Financial preparation is the single most important thing a first-time buyer can do before touring a single home. In a market like Fairport, where desirable homes attract offers within days, walking in without a pre-approval letter puts you at a serious disadvantage. The good news is that getting your finances in order is straightforward if you know what lenders are looking for.
Credit, Savings, and Debt-to-Income
Most conventional loan programs require a credit score of at least 620, though scores of 740 or higher unlock the best interest rates. FHA loans, which are popular with first-time buyers, allow scores as low as 580 with a 3.5 percent down payment, or as low as 500 with 10 percent down. Pull your credit reports from all three bureaus before you apply, dispute any errors, and avoid opening new credit accounts or making large purchases in the months leading up to your application.
Lenders also look at your debt-to-income ratio, which is your total monthly debt payments divided by your gross monthly income. Most lenders want this number below 43 percent for conventional loans, and ideally below 36 percent. If you carry student loans, car payments, or credit card balances, calculate where you stand before applying. Paying down revolving debt is one of the fastest ways to improve both your ratio and your credit score at the same time.
New York State offers first-time buyer assistance programs worth knowing about. The State of New York Mortgage Agency (SONYMA) provides low-interest mortgage programs and down payment assistance specifically for first-time buyers purchasing in New York. The Achieving the Dream program targets lower-income buyers, while the Low Interest Rate program is available to a broader range of income levels. Monroe County also periodically offers its own down payment assistance through community development programs, so it is worth contacting Monroe County's Office of Community Development to ask what is currently available.
Mortgage Pre-Approval in a Competitive Market
A pre-approval letter is not the same as a pre-qualification. Pre-qualification is a quick estimate based on information you self-report. Pre-approval means the lender has verified your income, assets, employment, and credit, and has committed to lending you up to a specific amount, subject to the property appraising. Sellers in Fairport, especially those receiving multiple offers, take pre-approval letters seriously and often discount or ignore offers that come in with only a pre-qualification.
Shop at least two or three lenders before committing. Local community banks and credit unions in the Rochester area sometimes offer competitive rates and faster turnaround times than large national lenders. Rate differences of even a quarter of a percent on a $350,000 loan translate to meaningful differences in your monthly payment and total interest paid over 30 years. The NAR's consumer guide to buying your first home has a clear breakdown of what to expect from the mortgage process at each stage.
3. Understanding the Full Cost of Buying in Fairport
The purchase price is only one part of what you will spend. First-time buyers in Fairport are often surprised by how much cash they need beyond the down payment. Budgeting for the full picture from the start prevents the kind of last-minute scramble that can derail a closing.
Down Payment and Closing Costs
Down payment requirements vary by loan type. Conventional loans with private mortgage insurance allow as little as 3 to 5 percent down. FHA loans require 3.5 percent. VA loans (for eligible veterans and service members) and USDA loans (for qualifying rural areas) can allow zero down, though Fairport itself is not typically in a USDA-eligible zone given its proximity to Rochester. If you put less than 20 percent down on a conventional loan, you will pay private mortgage insurance until you reach 20 percent equity.
Closing costs in New York State run higher than the national average. Buyers in Fairport should budget roughly 2 to 4 percent of the purchase price in closing costs, which include lender fees, title insurance, attorney fees (New York requires an attorney at closing), appraisal, home inspection, and prepaid items like homeowners insurance and escrow reserves. On a $350,000 home, that is $7,000 to $14,000 in addition to your down payment. For a full breakdown of what these line items look like locally, see the article on closing costs and transfer taxes when buying in Fairport.
Property Taxes and Monthly Payment Reality
Property taxes in Fairport are a significant part of your monthly housing cost. Monroe County and the Town of Perinton both levy taxes, and homes within the Fairport Central School District carry school taxes on top of that. Combined effective tax rates in this area can run between 2.5 and 3.5 percent of assessed value annually, which means a home assessed at $300,000 could carry $7,500 to $10,500 per year in property taxes, or $625 to $875 per month added to your mortgage payment. That is a meaningful number and one that first-time buyers sometimes underestimate when calculating what they can afford.
New York's STAR program can reduce your school tax bill if you own and occupy the home as your primary residence. The Basic STAR exemption is available to most homeowners, and the Enhanced STAR is available to qualifying seniors. Register with the New York State Department of Taxation and Finance after closing to claim it. For a complete picture of how property taxes affect your monthly payment in this area, the article on average property tax rates in Fairport, New York covers the numbers in detail.
4. The Home Search Process in Fairport
Once your finances are in order and your pre-approval is in hand, the search begins. Fairport and the surrounding Town of Perinton offer enough variety in housing styles, lot sizes, and locations that narrowing your criteria early makes the process much more efficient. Know your non-negotiables before you start touring: number of bedrooms, garage, basement, lot size, and maximum commute time to work.
Knowing Your Neighborhoods
The Erie Canal village area of Fairport has a walkable, small-town feel with access to shops, restaurants, and the canal towpath. Homes here tend to be older, with character details like original woodwork and covered porches, and lots are typically smaller. Moving further into Perinton, you find larger lots, more garage space, and neighborhoods built across several decades with a mix of ranch, colonial, and split-level styles. If you are curious about what daily life looks like in the canal village area specifically, there is a detailed look at the Erie Canal village area of Fairport and its walkability and amenities.
Commute distance matters too, and Fairport's position on Route 31F and near the I-490 corridor gives residents multiple ways to reach downtown Rochester. The drive to downtown Rochester is typically 20 to 30 minutes depending on traffic and route. RTS bus service connects Fairport to the broader Monroe County transit network, and the Erie Canal trail is a genuine multi-use corridor for cyclists and pedestrians. If commute logistics are a priority in your search, the article on commute options from Fairport to downtown Rochester covers the specifics.
What to Inspect and Why It Matters Here
Never skip the home inspection, regardless of market pressure. In Fairport, where a meaningful portion of the housing stock is 40 to 100-plus years old, inspections regularly turn up items like aging knob-and-tube wiring, galvanized water supply lines, older oil furnaces, and roofs approaching the end of their useful life. None of these are necessarily deal-breakers, but they are negotiating points and, more importantly, budgeting information you need before you commit.
In addition to a general home inspection, consider a sewer scope for older homes. Many Fairport-area homes built before 1980 have clay or Orangeburg sewer laterals that can deteriorate or collapse. A sewer scope inspection costs roughly $150 to $250 and can reveal problems that would cost thousands to repair after closing. If the home has a fireplace or wood-burning stove, a chimney inspection is also worth the modest additional cost.
5. From Offer to Closing: What First-Time Buyers Should Expect
The offer and contract phase is where first-time buyers most often feel overwhelmed, and where having an experienced local agent makes the biggest difference. Understanding the mechanics of an offer, what contingencies protect you, and how New York State's closing process works will help you move through this phase with confidence.
Making a Competitive Offer
In Fairport's current market, offering below list price on a well-priced home is rarely a winning strategy. Many homes in the $250,000 to $400,000 range receive multiple offers, and sellers are looking at price, financing type, contingencies, and closing timeline together. A strong pre-approval from a reputable lender, a reasonable inspection contingency, and a flexible closing date can make your offer more attractive even if you are not the absolute highest bid.
Earnest money is a good-faith deposit you submit with your offer, typically 1 to 2 percent of the purchase price. In New York, this money is held in escrow and applied toward your closing costs or down payment at closing. It is at risk if you walk away without a valid contingency reason, so understand your contract terms before signing. Your real estate attorney will review the purchase contract before you are legally bound, which is a protection specific to New York State's attorney-review process.
The Closing Timeline in New York State
New York State closings typically take 60 to 90 days from accepted offer to closing, which is longer than many other states. The process involves attorney review of the purchase contract, mortgage underwriting, appraisal, title search, and final walkthrough before closing. The closing itself takes place at a title company or attorney's office, and both buyer and seller are typically represented by their own attorneys. Budget for attorney fees of $800 to $1,500 on the buyer's side.
The final walkthrough happens within 24 to 48 hours before closing. This is your chance to confirm the home is in the agreed-upon condition, that any negotiated repairs have been completed, and that no new damage has occurred since your inspection. Do not skip it. Problems discovered after the deed transfers are your responsibility, so use the walkthrough to verify everything before you sign.
First-time buyers are navigating this process at a time when the market has become increasingly competitive. According to NAR data, first-time buyers now represent just 24 percent of all home purchasers nationally, a historic low, which means competition from repeat and investor buyers is real. Being prepared, moving quickly, and working with someone who knows the Fairport market well gives you the best shot at success.
FAQ
How much money do I need to buy my first home in Fairport, New York?
The total cash you need depends on your loan type, but plan for more than just the down payment. On a $330,000 home with a 5 percent conventional down payment, that is $16,500 down plus roughly $8,000 to $13,000 in closing costs, for a total of approximately $24,500 to $29,500 at closing. FHA loans reduce the down payment to 3.5 percent but add an upfront mortgage insurance premium. You will also want 2 to 3 months of mortgage payments in reserve after closing, as most lenders and financial advisors recommend that cushion. New York's SONYMA programs can provide down payment assistance to eligible first-time buyers, which can meaningfully reduce the cash required at closing.
Is Fairport, New York a good place to buy a first home right now in September 2026?
Fairport offers a real range of housing options across different price points, from smaller starter homes in the low $200,000s to larger move-in-ready homes in the $350,000 to $450,000 range. The market has remained competitive through 2026, with well-priced homes selling quickly, so first-time buyers need to be financially prepared and decisive. The Erie Canal village area, Perinton's established neighborhoods, and newer subdivisions on the eastern side of town each offer different tradeoffs in terms of lot size, home age, walkability, and price. Whether Fairport fits your budget and lifestyle is a personal decision, but the variety of housing stock means there is likely something at most price points for a prepared buyer.
Do I need a real estate attorney to buy a home in Fairport, New York?
Yes. New York State is an attorney-state for real estate transactions, meaning both buyers and sellers are expected to have their own attorneys review and negotiate the purchase contract before it becomes binding. This is actually a meaningful protection for first-time buyers: your attorney will review the contract terms, negotiate any changes, conduct the title search, and represent your interests at closing. Attorney fees on the buyer's side typically run $800 to $1,500 in the Monroe County area. Do not try to navigate a New York real estate transaction without one, even if the seller's agent suggests it is unnecessary.