← Back to Blog
Maine Home Buying
Buying a Maine Multifamily Home to Live In: What to Review Before You Offer
By Tony Duong, Broker Associate
Landing Real Estate · License # BA923377
October 26, 2026 · 3 min read
Rental income can help a household budget, but the building also becomes a business with existing obligations.
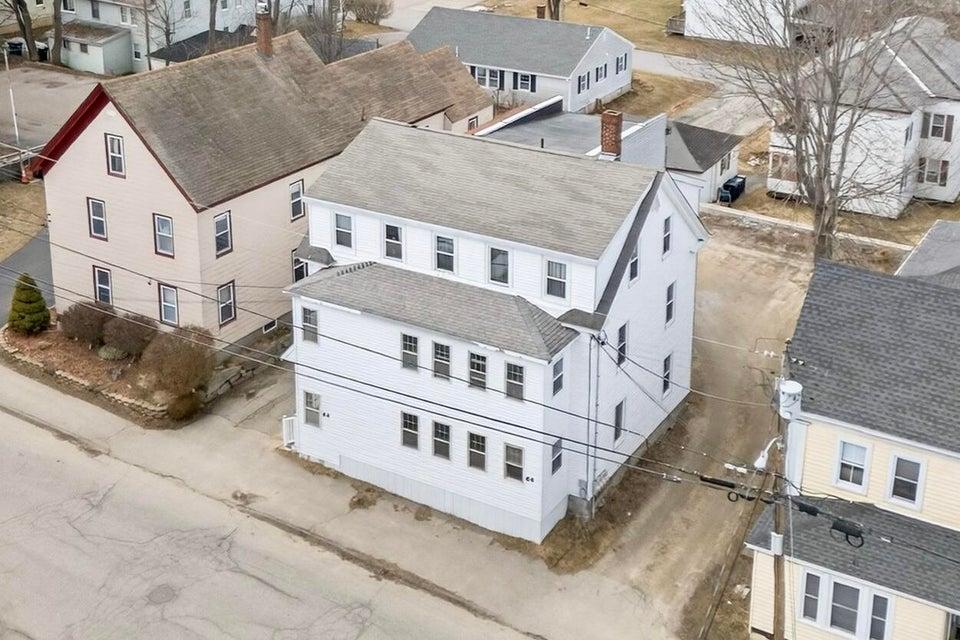
Before buying a Maine multifamily home to live in and rent out, verify the lawful unit count, review every tenancy and build a realistic operating budget. Then confirm financing for the property and your occupancy plan. Advertised rent is not the same as money available for your mortgage after expenses, vacancy and repairs.
Confirm which spaces are lawful dwelling units
Request municipal records for the approved use, unit count, permits and outstanding violations. Compare them with the listing, floor plan and current occupancy. An extra kitchen or separately advertised apartment does not establish lawful rental status.
Inspect the entire building, including common areas and systems serving multiple units. Ask about fire separation, exits, heating, electrical service and required approvals. Use qualified specialists where a general home inspection cannot resolve the question. Do not base your budget on a unit whose use remains uncertain.
Read the leases before projecting income
Obtain signed leases, amendments, a rent roll, payment history and the security-deposit accounting. Check renewal dates, concessions, utilities, parking and other promises. Ask your attorney how the purchase affects existing tenancies and what must transfer at closing.
Do not assume you can immediately occupy a rented unit or reset every rent to an advertised market figure. Have counsel review state and local requirements, notice obligations and any relevant rent rules. The Maine Attorney General’s tenant-rights guide is a useful starting resource for understanding landlord responsibilities.
Underwrite the building with expenses and reserves
Separate scheduled rent from actual collected rent. Request operating records and verify taxes, insurance, owner-paid utilities, maintenance and service contracts. Include vacancy, turnover, routine repairs and a reserve for major systems even if the seller reports unusually low recent spending.
Make one budget using documented current income and another showing a realistic interruption, such as a vacant unit or heating replacement. Keep your own housing payment and household reserves visible. The purchase should not depend on every tenant paying every month with no maintenance.
Ask the lender what income it can count
Provide leases, the unit configuration and your intended occupancy. Ask how the lender documents rental income, treats reserves and evaluates the property. A financing program’s treatment of projected rent may differ from the spreadsheet you use for your personal decision.
Also obtain insurance quotes that describe both owner occupancy and rental use accurately. Ask about liability, loss-of-rent coverage, deductibles and any building-condition requirements. Avoid assuming a standard single-family homeowners policy fits the arrangement.
Prepare to be a landlord from the first day
Create a plan for repairs, emergency calls, rent collection, recordkeeping and lawful tenant screening. Investigate applicable rental registrations, safety requirements and disclosures. Request the building’s radon records; Maine’s rental radon disclosure form illustrates documentation to review.
If you will use a manager, price the service and define who authorizes repairs. Before closing, reconcile deposits, keys, lease documents and tenant notices with your advisers. Your next step is a document review and operating budget, not a rent estimate copied from a listing. Resources reviewed October 26, 2026.
Request a guide for the purchase side
Get the free Maine Home Buyer’s Guide using the Home Buyer Guide name-and-email form. It covers the buying milestones while you and your advisers complete the additional rental-property review.
FAQ
Can I count all advertised rent toward my mortgage?
Do not assume so. Your lender determines qualifying income, and your personal budget should also account for expenses, vacancy and reserves.
Can I move into any unit after closing?
Existing tenancy rights and the lease may affect possession. Have an attorney review the specific unit and timing before making plans.
Does living in the building remove landlord obligations?
No. Determine which state and local requirements apply to your property and tenancy arrangement.